
Three years of Hertsmere's accounts carry disclaimed audit opinions. KPMG does not expect a clean one until 2027/28, the council's final year.
Hertsmere Borough Council’s accounts have gone three years running without an auditor being able to say whether they are right. The council’s auditors do not expect to sign off a clean set until the year the council ceases to exist.
That is set out in two KPMG reports that went to Hertsmere’s Audit Committee on Wednesday 23 September. They are published in full in the public agenda pack for the meeting.
What a disclaimer actually means
An auditor who cannot gather enough evidence to form an opinion issues a disclaimer of opinion. It is not a finding that anything is wrong. It is a statement that the auditor does not know.
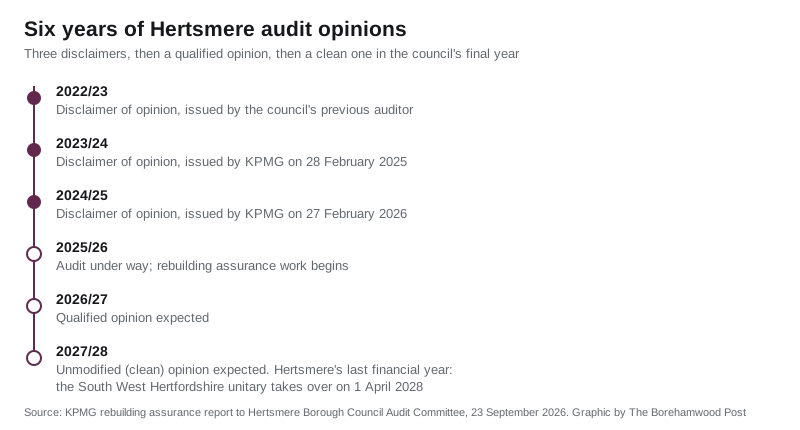
Hertsmere now has three in a row:
- 2022/23, disclaimed by the council’s previous auditor
- 2023/24, disclaimed by KPMG on 28 February 2025
- 2024/25, disclaimed by KPMG on 27 February 2026
Those two KPMG dates are not coincidences. They are the government’s statutory backstop dates. Ministers changed the Accounts and Audit Regulations in 2024 to clear a national backlog of unfinished local government audits. They set hard deadlines by which an audit report had to be published, finished or not. Councils across England were caught by it. Hertsmere was one of them.
The bit that is specific to Hertsmere
Clearing the backlog was the easy half. The second half is what the profession calls rebuilding assurance: going back over the disclaimed years until an auditor can stand behind the numbers again.
KPMG’s rebuilding assurance report, dated 29 July 2026, sets out five risks of material misstatement it has to clear at Hertsmere. All five run back through 2022/23, 2023/24 and 2024/25:
- property, plant and equipment: whether revaluation adjustments were correctly identified and classified
- property, plant and equipment: whether additions and disposals are properly supported
- the revaluation reserve: whether revaluation adjustments were accurately recorded
- earmarked reserves: whether movements in and out were accurately recorded
- the capital adjustment account: whether capital spending, disposals and revaluations were accurately recorded
On asset values, KPMG is blunt about its own record here. “During the past two audit cycles, we have been unable to successfully complete this testing,” the report says. The council values its land and buildings on a five-year rolling cycle. The firm therefore has to go back into the disclaimed years under the previous auditor, as well as the two years it could not finish itself.
The report also lists three reasons it could not get the assurance it needed in the 2024/25 audit, and what it wants Hertsmere to do about each:
- staff capacity issues: ensure enough appropriately skilled finance resource is available
- delays in provision of information: introduce a formal process for monitoring and escalating outstanding audit requests
- quality of accounts and supporting documentation: introduce a management review of audit evidence before it is handed to the audit team
Categorised B, and the timetable that follows
The Ministry of Housing, Communities and Local Government asked every audit firm to grade how hard each council will be to bring back to a normal audit, on a scale of A to D. KPMG has categorised Hertsmere as B: an audit “in theory capable” of supporting a compliant approach, but where “significant operational difficulties are likely”.
It gives three main reasons:
- the reserves and asset valuation work set out above
- the pressure local government reorganisation will put on the same senior officers
- the council’s own capacity to support an audit
The report’s own timetable then says when readers should expect the numbers to mean something again:
- a qualified opinion for the year ending 31 March 2027
- an unmodified opinion, the clean one, for the year ending 31 March 2028
Why that date matters
The year ending 31 March 2028 is Hertsmere Borough Council’s last.
KPMG’s report sets out the reorganisation timetable itself. The government’s preferred option for Hertfordshire is four new unitary councils. The proposed South West Hertfordshire authority would be made up of Hertsmere, Three Rivers and Watford. Elections to the shadow authorities are scheduled for May 2027, and the new unitary councils take over service delivery from 1 April 2028.
So on the auditors’ own plan, the first clean set since the backlog began would be the accounts for the council’s final year. They would be signed off after it has gone.
What it costs
KPMG’s fee for the risk assessment stage alone is £29,255 plus VAT. It estimates the substantive stage, the actual re-testing, at £30,000 to £40,000 plus VAT. The firm notes that the fees are subject to the Public Sector Audit Appointments variation process and that MHCLG has announced grant funding for this work.
Separately, the draft external audit plan for 2025/26 was also before the committee. It sets materiality for the consolidated accounts at £2.4m, or 2.3 per cent of expenditure, with performance materiality of £1.56m, and says misstatements above £0.12m will be reported to councillors. It names three significant risks for the current year’s audit: the valuation of land and buildings, the valuation of the pension obligation, and management override of controls. The plan is dated 30 June 2026 and is still marked draft.
What it means for you
Nothing about a disclaimer says money is missing. It says nobody independent has been able to confirm the figures.
What that removes is the check. The accounts cover your council tax, the parking income, the developer money the council allocates, the reserves it draws on to balance a budget and the value it puts on its own land and buildings. For three years those numbers have gone out unverified. The work to verify them now runs alongside the biggest administrative change in the borough since 1974.
Practical things you can do:
- Read the accounts yourself. Hertsmere publishes them, including the draft 2025/26 set, on its financial documents page, along with the annual notice of your right to inspect them.
- Watch the Audit Committee. Its papers are published in advance on the council’s committee site, and the next risk report is due at the meeting on 26 January 2027.
- If the figures matter to a decision near you, our coverage of where the council’s developer money goes is in Borehamwood planning news, and the bands behind your own bill are in Borehamwood council tax bands.
Sources
- Hertsmere Borough Council, Audit Committee, 23 September 2026, agenda and reports pack.
- KPMG, Rebuilding assurance update, report to the Audit Committee for the year ending 31 March 2026, 29 July 2026, for the three disclaimers and their dates, the five risks of material misstatement, the three drivers of the lack of assurance, the category B assessment, the expected opinions and the fees.
- KPMG, Draft external audit plan and strategy for the year ending 31 March 2026, 30 June 2026, for materiality, the reporting threshold and the significant risks.
- Hertsmere Borough Council, financial documents, for the published statements of accounts and notices of inspection.
Have your say